Selling to Uncle Sam: The Founders Cracking a $2 Trillion Market the Disrupt 500 Forgot
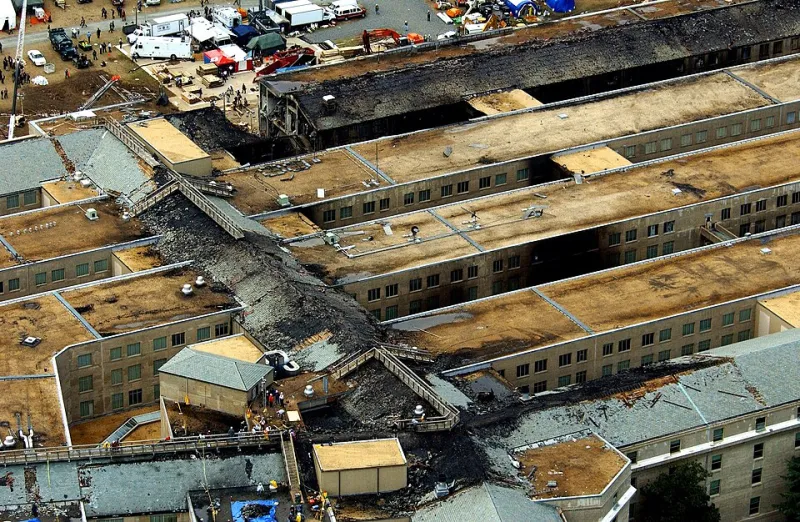
Photo: DoD photo by Tech. Sgt. Cedric H. Rudisill., Public domain, via Wikimedia Commons
Somewhere between the Pentagon's budget authorization and a small-business set-aside contract sits the strangest irony in American venture capital: the United States government spends roughly $2 trillion annually on procurement, and yet when the Disrupt 500 compiled this year's ranking of the country's fastest-disrupting startups, companies selling into that machine could be counted on one hand.
For decades, the math made a cold kind of sense. Government sales cycles stretch eighteen months to three years. Payment terms reward the patient and punish the undercapitalized. And venture funds raised on ten-year horizons have little appetite for a customer whose fiscal year resets every October and whose priorities reset with every election.
But the founders who've pushed through anyway tell a different story — one that suggests the moat protecting incumbents is starting to erode.
The Two-Year Yes
Consider the arc most federal-first founders describe. A pilot in year one. A blank stare at year two. Then, almost without warning, a sole-source award and a line item in an appropriations bill that changes the company's trajectory overnight.
"I told our investors we'd have revenue in twelve months," one defense-logistics founder recalls. "We had a purchase order in month twenty-six. The difference between those two sentences is the entire govtech category."
That founder's company survived the gap on SBIR grants and a bridge round priced brutally low. Many don't. The graveyard of govtech is filled with teams whose runway expired one quarter before the contract landed.
Why the Wall Is Cracking Now
Three forces are converging to change the risk calculus.
First, the procurement-reform wave associated with the DOGE era has put spending under a microscope, and scrutiny cuts both ways. Legacy contractors built on cost-plus paperwork are suddenly vulnerable to line-item challenges in a way they haven't been since the 1990s.
Second, the software talent pool has shifted. A generation of engineers raised on commercial SaaS economics is increasingly willing to take the security clearance and the mission, especially as commercial AI markets crowd and differentiate on thin margins.
Third, and least discussed: the revenue model is changing. The new cohort isn't waiting on appropriations riders. They're selling subscription tools to the program offices directly — sometimes on government purchase cards, sometimes through OTA agreements that sidestep the traditional contracting apparatus entirely.
The Playbook Shift
The founders most likely to populate future Disrupt 500 lists share a few operating patterns:
- Credit card revenue before contracts. Charge a program office $40,000 on a purchase card before you ever speak to a contracting officer. It proves demand and de-risks the formal award.
- One agency, deeply. The winners pick a single office with a painful, budgeted problem and refuse to diversify until they own it.
- Compliance as a moat. FedRAMP, CMMC, and clearance infrastructure are expensive, but they're also barriers that keep out the flat-in-a-year competitors plaguing commercial software.
- Patient capital, structured differently. Revenue-based financing, defense-focused funds, and strategic corporate money are replacing the standard seed check that was never built for an eighteen-month sales cycle.
Who Blinks First
The open question is whether mainstream venture capital moves before the opportunity is consolidated. The government is not a market that rewards late entrants — incumbent relationships compound for decades, and the set-aside programs that favor small businesses have revenue ceilings that expire fast.
What's certain is that the blind spot is now documented. When $2 trillion of annual spending produces a rounding error in a ranking of America's most disruptive companies, the dislocation isn't in the government. It's in the market's assumptions.
The next Disrupt 500 may look back at this year's list the way later generations looked at pre-2001 defense spending: a period when the largest customer on earth was sitting quietly, under-served, waiting for someone to build for it.